
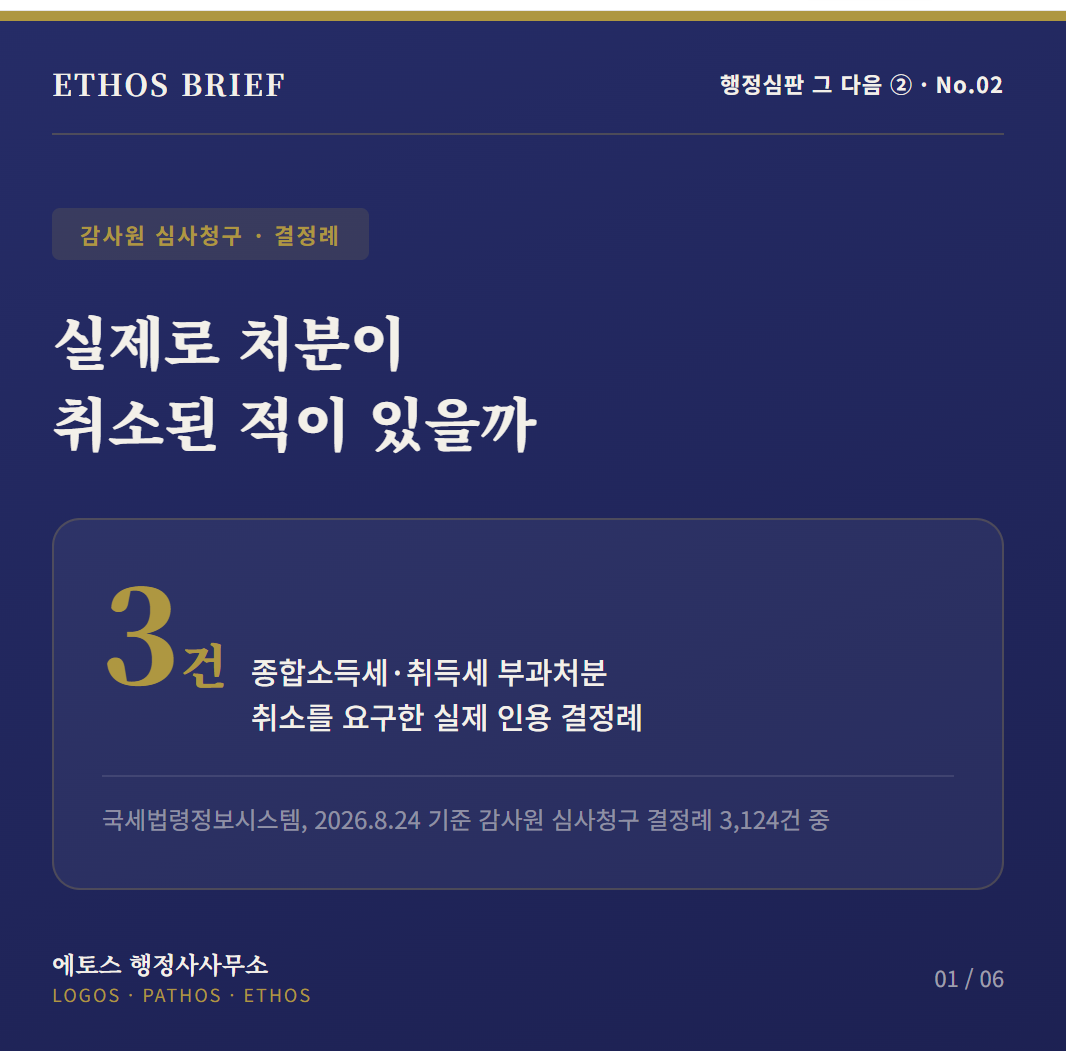
[Beyond Administrative Appeals ②] The Board of Audit and Inspection Can Require an Agency to Cancel Its Disposition — Three Favorable Decisions Explained
Hello, this is Jean, a licensed administrative agent in Korea.
When someone receives an unfavorable decision from a government agency, the first term they usually search for is “administrative appeal.”
That is understandable. An administrative appeal is one of the best-known ways to challenge administrative measures such as a business suspension, administrative surcharge, license revocation, or tax assessment.
Before filing an administrative appeal, however, it is worth checking whether another remedy may be available. An administrative appeal is not the only way to challenge an administrative disposition in Korea.
One possible alternative is a request for examination by the Board of Audit and Inspection of Korea under Article 43 of the Board of Audit and Inspection Act.
Depending on the case, this procedure may need to be considered separately from an administrative appeal. In some matters, the procedure chosen at the beginning can also affect the options available later.
The problem is that this remedy is not widely known.
There is plenty of information about administrative appeals, but it is much harder to find a single source explaining how to file a request for examination by the Board of Audit and Inspection, how it differs from an administrative appeal, and how the Board has decided actual cases.
In this “Beyond Administrative Appeals” series, I will examine the Board of Audit and Inspection’s examination procedure one issue at a time.
Beyond Administrative Appeals Series
- [Beyond Administrative Appeals ①] There Is Another Remedy: Requesting an Examination by the Board of Audit and Inspection
- [Beyond Administrative Appeals ②] Has the Board Ever Required an Agency to Cancel a Disposition? — Analysis of Actual Decisions
- [Beyond Administrative Appeals ③] Administrative Appeal vs. BAI Examination Request: Which Procedure Should You Choose?
- [Beyond Administrative Appeals ④] What Should Be Included in a BAI Examination Request? — Requested Relief, Grounds, and Evidence
When I explain this procedure, one question comes up repeatedly:
“I understand that the system exists, but has the Board ever actually required an agency to cancel an administrative disposition?”
Yes. There are actual published decisions.
The published examination decisions include cases in which the Board required the relevant agency to cancel the following dispositions:
- A comprehensive income tax assessment of KRW 20,008,900
- Acquisition tax and related taxes totaling KRW 88,503,590
- The denial of a claim for reassessment involving acquisition tax and related taxes totaling KRW 7,263,458,190
These claims were not accepted simply because the claimant appeared to have suffered an unfair result or because the amount at issue was substantial.
In each case, the Board identified a specific problem. The agency had incorrectly interpreted the law, incorrectly assessed the facts underlying the disposition, or incorrectly applied the relationship between multiple statutes and tax-reduction requirements.
This article examines three favorable decisions and the particular part of each disposition that the Board found problematic.
If You Have Not Read Part ①
Part ① explains the purpose of a request for examination by the Board of Audit and Inspection, how it differs from an administrative appeal, the filing period and procedure, and the scope of services that an administrative agent may provide.
Part ② focuses on the legal issues and reasoning found in actual decisions.
If this is your first time hearing about a BAI examination request, you may wish to read Part ① first.
Read Part ①
There Is Another Remedy: Requesting an Examination by the Board of Audit and Inspection
Does the Board of Audit and Inspection Directly Cancel the Disposition?
The legal structure should be distinguished carefully.
Under Article 46 of the Board of Audit and Inspection Act, if the Board determines that a request has merit, it requires the head of the relevant agency to take corrective or other necessary measures.
Article 47 provides that the head of the relevant agency must take action in accordance with the Board’s decision.
This differs from a court directly canceling an administrative disposition through a judgment.
The operative language in actual BAI decisions can nevertheless be quite specific:
“The disposition agency shall cancel the disposition imposed on the claimant.”
This is more than an informal recommendation to review the matter again.
However, a published decision alone may not establish exactly when the relevant agency completed its subsequent cancellation process. For legal accuracy, this article therefore states that the Board “required the disposition agency to cancel the disposition.”
Three Favorable Decisions Examined in This Article
1. BAI Review Decision 2023-360
- Disposition challenged: Comprehensive income tax assessment of KRW 20,008,900
- Decision: The agency was required to cancel the assessment
- Central issue: Statutory interpretation
2. BAI Review Decision 2022-1577
- Disposition challenged: Acquisition tax and related taxes totaling KRW 88,503,590
- Decision: The agency was required to cancel the assessment
- Central issue: Assessment of the facts and legal characterization
3. BAI Review Decision 2021-860
- Disposition challenged: Denial of a claim for reassessment involving KRW 7,263,458,190 in acquisition tax and related taxes
- Decision: The agency was required to cancel the denial
- Central issue: Tax-reduction requirements and the relationship between applicable statutes
The facts and amounts involved in these three cases are different.
When the decisions are examined together, however, they reveal the points at which the legal and factual foundation of an administrative disposition may become vulnerable during a BAI examination.
Case ① Incorrect Application of the Law
BAI Review Decision 2023-360 / October 17, 2024
Comprehensive income tax assessment of KRW 20,008,900
The first case concerned an income deduction for investments in a venture company.
The claimant invested a total of KRW 325,000,000 in a venture company between 2018 and 2020.
The central issue was which taxable year’s comprehensive income should be used to calculate the limit on the income deduction.
The disposition agency concluded that the deduction limit should be calculated by reference to the comprehensive income for each year in which the investments were made.
It determined that the claimant had taken an excessive deduction and assessed KRW 20,008,900 in comprehensive income tax for the 2020 taxable year.
The Board of Audit and Inspection reached a different conclusion.
The relevant provision allowed the investor to select, within a specified period, the taxable year in which the income deduction would be claimed.
The Board therefore concluded that the term “relevant taxable year,” as used to determine the deduction limit, should refer to the taxable year selected for the deduction rather than necessarily the year in which the investment was made.
The operative part of the decision stated:
“The disposition agency shall cancel the assessment of KRW 20,008,900 in comprehensive income tax for the 2020 taxable year imposed on the claimant on May 10, 2023.”
— BAI Review Decision 2023-360, October 17, 2024
The Most Important Point Is Not the KRW 20 Million
The claim was not accepted because the amount of tax was substantial or because the claimant’s personal circumstances appeared sympathetic.
The decisive question was whether the agency’s interpretation and application of the law were correct.
The fact that a government agency cites a statutory provision in its notice does not necessarily mean that its interpretation and application of that provision are correct.
The following questions may need to be examined:
- Did the agency effectively add a requirement that does not appear in the statute?
- Did it interpret the statutory language too narrowly or too broadly?
- Are there court precedents or prior administrative decisions interpreting the same language?
- Is the agency’s interpretation consistent with the overall structure of the statute?
- Does the interpretation produce a result that conflicts with the purpose of the制度?
If these questions arise when reviewing the notice of disposition, statutory interpretation itself may become a central issue in the challenge.
There is a significant difference between saying:
“This disposition is unfair.”
and stating:
“The agency incorrectly interpreted the term ‘A’ in Article X of the relevant Act as meaning ‘B.’”
The second approach identifies the legal issue that must actually be decided.
Case ② Does a Transfer Labeled as a “Gift” Constitute a Gift in Substance?
BAI Review Decision 2022-1577 / June 27, 2024
Acquisition tax and related taxes totaling KRW 88,503,590
The second case concerned acquisition tax on real property used by a religious organization.
A church acquired real property for religious purposes and received an acquisition tax exemption. The church later transferred title to a maintenance foundation affiliated with its religious denomination.
The disposition agency characterized the transfer as a “gift.”
It concluded that gifting tax-exempt property triggered recapture of the exemption and assessed acquisition tax, local education tax, and special tax for rural areas totaling KRW 88,503,590.
Viewed only from the registration record, the issue may appear straightforward:
“Title was transferred from the church to the maintenance foundation, so was it not a gift?”
The Board did not determine the legal character of the transaction solely from the formal transfer of title.
It also examined matters including:
- The denomination’s internal rules
- Who actually used and benefited from the property
- Who paid the expenses associated with its management
- Who held effective authority to dispose of the property
- The legal relationship between the religious organization and the maintenance foundation
Even after the title transfer, the original church continued to use and manage the property as a religious facility.
The Board concluded that the transfer to the maintenance foundation could not be treated in the same way as a “gift” constituting grounds for recapture under the Restriction of Special Local Taxation Act.
The Board therefore required the agency to cancel the assessment of KRW 88,503,590.
Start by Reexamining the Facts Underlying the Disposition
The first case concerned the interpretation of statutory language.
In the second case, the important question was whether the facts and legal characterization assumed by the agency were correct.
The agency had an objective document showing the transfer of ownership. The legal relationship governing the entire matter, however, could not be determined solely from the appearance of the title transfer.
It was necessary to examine:
- Who actually used the property
- Who paid the management expenses
- Why title was transferred
- What the denomination’s internal rules provided
- Who held the substantive rights relating to the property
Most administrative dispositions are based on certain assumed facts.
If the underlying facts or their legal characterization cannot be sustained, the disposition built on that foundation may also need to be reconsidered.
Applying This Reasoning to Your Own Case
It may be useful to determine whether the agency treated one of the following items as virtually conclusive:
- The title of a contract
- The registered owner shown in the property records
- Wording used in a filing or report
- A photograph taken at a particular point in time
- One person’s statement
- A limited portion of the transaction history
- Internal government records
This does not necessarily mean that the document or record is incorrect.
The important question is whether that single item sufficiently proves all the facts recognized by the agency.
Where the formal documentation differs from the actual transaction, use, or management arrangement, the following materials may become important evidence:
- Contracts
- Bank transaction records
- Meeting minutes
- Internal rules
- Utility payment records
- Photographs
- Emails
- Official correspondence
- Written confirmations
Case ③ The Finding That the Statutory Requirements Were Not Met Was Incorrect
BAI Review Decision 2021-860 / December 21, 2023
Denial of a claim for reassessment involving KRW 7,263,458,190 in acquisition tax and related taxes
The third case involved a considerable amount.
A real estate investment company established to construct and lease youth housing near a subway station acquired land for the project.
The claimant argued that the acquisition qualified for an acquisition tax reduction and filed a claim for reassessment.
The disposition agency rejected the claim involving acquisition tax and related taxes totaling KRW 7,263,458,190.
There were two principal issues:
- Did the acquisition of the land qualify for the acquisition tax reduction provided by law?
- Would applying both the tax-reduction provision and the standard tax-rate provision constitute a duplicate tax reduction?
The Board examined matters including:
- The application for registration as a rental business
- The business purpose stated in the authorization granted to the real estate investment company
- The actual progress of the project
- The applicable statutes
- The legislative history of the relevant provisions
The Board concluded that the acquisition qualified for the tax reduction.
It also determined that applying the standard acquisition tax rate under the Local Tax Act together with the tax-reduction provision did not constitute a duplicate tax reduction.
The operative part of the decision stated:
“The disposition agency shall cancel its denial, dated November 16, 2020, of the claimant’s claim for reassessment involving acquisition tax and related taxes totaling KRW 7,263,458,190.”
Break Down the Statement “You Did Not Meet the Requirements”
Notices of administrative dispositions frequently contain statements such as:
- “The relevant requirements have not been met.”
- “You do not qualify for the program.”
- “The property cannot be considered eligible for the tax reduction.”
- “The licensing requirements have not been satisfied.”
When considering a challenge, these statements should not simply be accepted as conclusions.
The specific requirement in dispute should be identified.
If the law requires A, B, and C, it is necessary to determine whether the agency disputed A, B, or C.
It is also necessary to consider whether the agency effectively required D even though D does not appear in the law.
Tax, licensing, registration, subsidy, and exemption cases often involve multiple statutes, enforcement decrees, enforcement rules, and administrative notices.
An incorrect understanding of the relationship between those rules may change the outcome of the disposition.
Comparing the Three Decisions
Statutory Interpretation
- Case: BAI Review Decision 2023-360
- Question to ask: Was the statute interpreted correctly?
Facts and Legal Characterization
- Case: BAI Review Decision 2022-1577
- Question to ask: Were the facts underlying the disposition and their legal characterization correct?
Statutory Requirements and Interaction Between Laws
- Case: BAI Review Decision 2021-860
- Question to ask: Were the statutory requirements and the relationship between multiple laws applied correctly?
The amount that the agency was required to cancel is not the only important aspect of these decisions.
More importantly, the Board did not merely review the final result. It reexamined the legal and factual premises that led to that result.
A Strong Challenge Does Not Attack Only the Final Conclusion
An administrative disposition is generally constructed as follows:
Fact A exists.
→ Law B applies.
→ The requirements of legal category C are satisfied.
→ Therefore, disposition D is imposed.
When reviewing a possible challenge, the analysis should proceed in reverse:
Is Fact A correct?
→ Is there sufficient evidence supporting Fact A?
→ Does Law B actually apply?
→ Has Law B been interpreted correctly?
→ Are the requirements of C actually satisfied?
→ If not, can disposition D still be maintained?
In each of the three cases examined above, one part of this chain failed, leading the Board to determine that the disposition should be canceled.
“Why Are All Three Examples Tax Cases?”
That is correct. The favorable decisions introduced in this article concern comprehensive income tax and acquisition tax.
As of August 24, 2026, the National Tax Law Information System displayed a total of 3,124 BAI examination decisions. A substantial proportion of the published decisions concern taxation.
This does not mean that the BAI examination procedure is limited to tax cases.
Article 43 of the Board of Audit and Inspection Act allows an interested person to request an examination regarding a disposition or other act connected with the duties of an entity or person subject to audit by the Board.
Whether a particular matter is eligible must still be determined individually by considering matters including:
- The nature of the disposition
- The claimant’s legal standing
- The relationship with other available appeal procedures
- Statutory exclusions under the Board of Audit and Inspection Act
The cases selected for this article involve tax matters because their issues and reasoning can be explained relatively clearly.
The message is not that every tax case should be taken to the Board of Audit and Inspection.
The important point is that the Board has reexamined the legal and factual premises of administrative dispositions and, where it found an error, required the relevant agency to take corrective action, including cancellation.
This Does Not Mean That BAI Examination Requests Are Easily Accepted
The cases discussed above are favorable decisions.
Not every request is accepted. Even where a claimant presents a seemingly favorable prior decision, the request may be rejected if the material facts are different.
BAI Review Decision 2025-161 / April 13, 2026
This case concerned whether an import declaration could be withdrawn so that a lower tariff rate could be applied.
The claimant argued that the customs broker had made an error and referred to a prior Korea Customs Service decision permitting withdrawal of an import declaration.
The Board did not accept the argument.
It concluded that once the tax liability had arisen and become fixed through the import declaration, the desire to obtain a lower tariff rate did not by itself justify withdrawal of that declaration.
The Board also determined that the prior decision presented by the claimant involved materially different facts and could not be applied directly.
The lesson is clear:
“A favorable decision exists” and “that decision applies to my case” are two different propositions.
Cases are not identical simply because the dispositions have the same name.
Even among acquisition tax cases, the actual issue may concern:
- The date of acquisition
- The tax base
- Tax-reduction requirements
- The identity of the actual acquirer
- Whether a shareholder is a controlling shareholder
- Whether a title-trust arrangement exists
It is not enough to locate one favorable decision and argue:
“That case was canceled, so my disposition must also be canceled.”
The applicable statutory provisions, legal requirements, and material facts must be compared.
What to Examine Before Focusing on the Word “Cancellation”
1. The Issue in Dispute: What Did the Board Actually Decide?
The fact that two cases involve the same type of disposition is less important than whether they involve the same legal issue.
For example, the fact that both matters concern acquisition tax is less significant than the specific question:
“Did a transfer of title between a religious organization and its maintenance foundation constitute a gift triggering recapture?”
2. The Agency’s Position: How Did the Other Side Respond?
An administrative challenge does not consider only the claimant’s arguments.
The disposition agency also explains why it believes the disposition was lawful.
When reading a decision, it is necessary to examine:
- What the claimant argued
- How the disposition agency responded
- Why the Board accepted or rejected the agency’s response
When preparing an actual case, it is not enough to explain why your position is correct. You should also anticipate the arguments the disposition agency is likely to make.
3. The Board’s Reasoning: How Were the Law, Facts, and Evidence Connected?
It is necessary to identify:
- Which statutes the Board applied
- Which facts the Board accepted
- Which precedents or legal principles it considered
- Why it concluded that the agency’s determination was correct or incorrect
The most useful part of a favorable decision is not simply the result. It is the reasoning that led to that result.
Should You Search for Similar Decisions in Your Own Case?
If you have received a notice of disposition, consider the following questions:
- [ ] Is it unclear from the notice which requirement the agency believes was not satisfied?
- [ ] Do you and the agency interpret the same statutory provision differently?
- [ ] Are you asking, “Does the law really require this?”
- [ ] Does it appear that important evidence you submitted was not adequately considered?
- [ ] Is there a difference between the formal documentation and the actual facts?
- [ ] Do you believe the agency incorrectly recognized a material fact?
- [ ] Are you aware of similar cases reaching a different conclusion?
- [ ] Did the agency omit an important circumstance when exercising its discretion?
- [ ] Does the disposition involve several laws with a complicated relationship?
Checking several items does not mean that the disposition will necessarily be canceled.
It may, however, indicate that the legal and factual premises of the disposition should be reviewed again.
Three Things to Mark First in a Notice of Disposition
1. The Legal Basis for the Disposition
Identify the statute and specific article relied on by the agency.
2. The Facts Recognized by the Agency
Determine which facts led the agency to conclude that the relevant statutory requirements were satisfied.
3. The Sentence Connecting the Facts to the Final Conclusion
Locate the part of the notice that effectively states:
“Because Fact A exists, disposition B is imposed.”
The next step is to examine the matter in the following order:
Law → Facts → Evidence → Prior Decisions
An administrative challenge cannot be completed merely by providing a lengthy explanation of why the outcome feels unfair.
The first task is to identify exactly which part of the disposition is incorrect and why.
If You Want to Know Whether Similar Decisions Exist
Finding a favorable case online is less important than determining whether the legal reasoning in that case can be applied to your own matter.
When reviewing a notice of disposition and the related records, Ethos Administrative Agent Office examines the following:
- The central issue underlying the disposition
- The facts assumed by the disposition agency
- The applicable statutes and statutory requirements
- Similar BAI examination decisions and administrative appeal decisions
- The similarities and differences between the prior decision and the client’s case
- Arguments the disposition agency may raise in response
- Available challenge procedures and the recommended structure of written submissions
We do not immediately conclude that a claim has merit simply because a similar favorable decision exists.
The first question is whether the reasoning in that decision can actually be applied to the matter under review.
Preliminary Review and Formal Consultation
For those who are unsure whether a formal consultation is necessary, we provide a preliminary review based on the notice of disposition.
Preliminary Review
The preliminary review considers:
- What type of disposition was imposed
- Whether an administrative challenge should be considered
- What additional records may be required
Formal Review and Consultation
Where a detailed analysis is required, the review may include:
- Analysis of the legal basis and applicable statutes
- Identification and organization of the central issues
- Review of the facts and supporting evidence
- Comparison with BAI examination decisions and administrative appeal decisions
- Assessment of likely counterarguments from the disposition agency
- Organization and preparation of documents related to the examination request
The amount involved and the word “cancellation” are not the only matters that should be examined in a favorable decision.
The important questions are why the Board determined that the disposition should be canceled and whether the same reasoning can be applied to the case under review.
A strong administrative challenge does not attack only the conclusion. It begins by testing each legal and factual premise that led to that conclusion.
Frequently Asked Questions
Q. Does the Board of Audit and Inspection issue decisions requiring the cancellation of administrative dispositions?
Yes.
As the cases discussed above demonstrate, the Board has issued decisions requiring disposition agencies to cancel comprehensive income tax assessments, acquisition tax assessments, and denials of claims for reassessment.
However, the Board does not directly cancel a disposition in the same way that a court does through a judgment.
The Board requires the head of the relevant agency to take corrective or other necessary measures, and the agency must act in accordance with the Board’s decision.
The outcome of another case is not guaranteed because the applicable statutes and material facts may differ.
Q. If a similar favorable decision exists, can my disposition also be canceled?
A single prior decision is not enough to make that determination.
The relevant question is not whether the dispositions have similar names. It is whether the applicable statutory provisions, central legal issues, and material facts are genuinely comparable.
It is also important to identify how your case differs from the favorable decision, not only how it is similar.
Q. What should I examine in a BAI decision?
Do not read only the operative part of the decision.
The following order is useful:
Issue in dispute → Recognized facts → Claimant’s arguments → Agency’s position → Applicable laws → Board’s reasoning
In particular, reviewing how the Board addressed the disposition agency’s counterarguments can help when structuring a written challenge.
Q. Is a BAI examination request more advantageous than an administrative appeal?
The existence of favorable BAI decisions does not mean that a BAI examination request is always more advantageous.
The appropriate procedure depends on factors including:
- The type of disposition
- The specific law governing the matter
- Whether each procedure is available
- Existing BAI and administrative appeal decisions
- The relationship between the selected procedure and any later administrative litigation
Which Procedure Should You Choose?
After reading this far, one question naturally remains:
“If both an administrative appeal and a BAI examination request are available, should I choose the procedure with more favorable decisions?”
The decision is not that simple.
It is necessary to consider:
- The nature of the disposition
- The statutes that apply
- The body of prior decisions under each procedure
- The effect of that choice on later procedures
The next article will compare these issues in more detail.
[Beyond Administrative Appeals ③] Administrative Appeal vs. BAI Examination Request: Which Procedure Should You Choose?