
[Business Transfers and Regulatory Permits ③] A Business Transfer Agreement Needs More Than the Goodwill Price — Regulatory Succession Clauses and Contract Terms to Review
Hello, this is Administrative Scrivener Ji Sang-jin.
According to data from Korea’s Ministry of SMEs and Startups based on National Tax Service statistics, approximately 986,000 businesses closed in 2023, approximately 1.008 million in 2024, and approximately 976,000 in 2025.
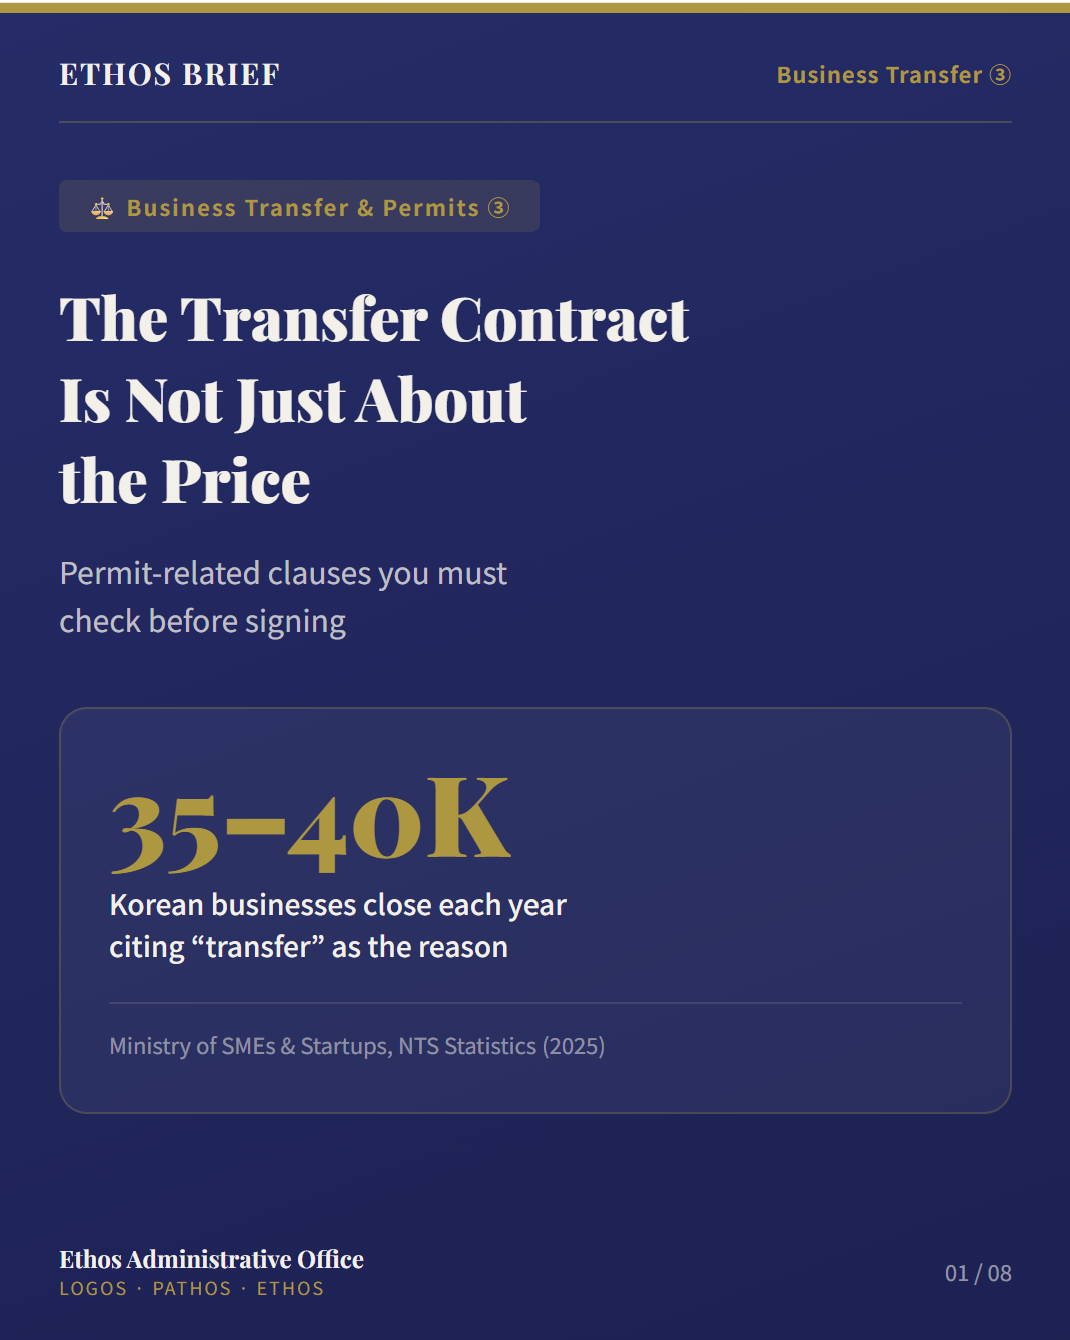
Each year, approximately 35,000 to 40,000 businesses close for reasons classified as a “transfer or acquisition.”
In other words, while some business owners exit, tens of thousands of businesses are also transferred to new operators every year.
When acquiring a store or an existing business, most buyers naturally begin with revenue and goodwill.
How much is the monthly revenue?
How much is the rent?
Which facilities and equipment are included in the transaction?
But if the business operates under a permit, registration, or statutory business report, there is one more question to ask.
Who is currently registered as the operator under the relevant permit, registration, or business report?
Acquiring a business by contract and acquiring the administrative status required to operate that business legally are not necessarily the same thing.
Restaurants, hotels, salons, gyms, and other regulated businesses may require a separate administrative procedure for succession to operator status.
This article focuses on the contract terms and clauses that should be reviewed when acquiring a regulated business in Korea.
The Agreement Has a Closing Date — But Does It Have a Deadline for the Seller’s Obligations?
Open a typical business transfer agreement.
The dates relating to money are usually very precise.
- Deposit: ○○
- Final payment: ○○
- Handover of the premises: ○○
But there are agreements that do not clearly state when the seller must complete the obligations required for regulatory succession.
When must the seller provide the necessary documents?
What if an additional signature or seal is required?
Who will deal with an existing licensing or registration issue that must be corrected first?
What if the competent authority requests supplementary documents?
If the final payment date is clearly fixed but these matters are not, the sequencing of the transaction should be reviewed again.
The important point in regulatory clauses is not how many special provisions are inserted into the agreement.
It is deciding what the seller must complete before the buyer pays the final balance.
A problem that can be structured as a contractual condition before closing may become a request for cooperation—or even a dispute—after the purchase price has already been paid.
A business transfer agreement for a regulated business should therefore be more than a document recording “how much the business was sold for.”
It should structure the seller’s obligations and the sequence of payment so that the buyer can actually complete the regulatory succession.
A Significant Number of Businesses Are Transferred Rather Than Simply Closed
According to Ministry of SMEs and Startups data based on National Tax Service statistics, approximately 976,000 businesses closed in 2025.
Among the reported reasons for closure, 3.6% were classified as “transfer or acquisition.”
A simple calculation produces approximately 35,000 businesses.
This figure should not be treated as the exact number of business transfer agreements executed during the year.
It does, however, show that a substantial number of businesses are transferred to another operator rather than simply discontinued.
Finding a buyer and recovering the economic value of a business can also be difficult.
In a Ministry of SMEs and Startups survey of 1,500 small business owners who had experienced closure within the previous year and participated in relevant government programs, the average period from deciding to close until cancellation of the business registration was 7.7 months.
Among the reasons for the delay, 30.6% cited difficulty finding a new buyer or transferee, while 30.7% identified recovery of deposits and goodwill as a difficulty during the closure process.
Source: Ministry of SMEs and Startups, June 30, 2026, “MSS Examines Everything From the Scale of Business Closures to the Reasons Behind Them Through Data”
It is therefore understandable that both sellers and buyers spend significant time negotiating price.
How much goodwill should be paid?
How should the facilities be valued?
How large should the deposit be?
When should the final payment be made?
But when acquiring a regulated business, the sequence of payment can be just as important as the amount.
And that sequence should be considered together with the regulatory succession procedure.
What If the Seller Refuses to Cooperate After the Contract Is Signed?
A dispute involving a hotel in Jeju eventually reached the Korean Supreme Court.
The management association representing the sectional owners of the hotel and the existing hotel operator agreed that once a new management company was selected, the existing operator would terminate its hotel operation and cooperate in changing the business registration to the new operator.
A new operator was selected.
But the succession of operator status was not completed.
The dispute ultimately developed into litigation over whether the existing operator was required to cooperate with the succession filing procedure.
This became Supreme Court Decision 2018Da259565, January 27, 2022.
The Supreme Court held that when the competent authority accepts a succession filing for a public sanitation business, a public-law legal effect arises through the change of operator status.
The Court also held that the documents submitted in the succession process do more than simply prove that the business has been transferred.
They may also function in relation to the existing operator’s intention to terminate the business.
Accordingly, the Court recognized that cooperation from the transferor may be necessary for the transferee to complete the succession filing.
In practical contract terms, the conclusion is straightforward.
The seller’s cooperation is not something the buyer should simply request after closing.
It should be structured as a contractual obligation from the beginning.
The important point is therefore not simply to state that the seller has certain obligations.
Those obligations should also be connected to the sequence of payment.
The Business Transfer Agreement May Also Become Part of the Regulatory Succession Procedure
As of September 2026, Article 48 of the Enforcement Rule of the Korean Food Sanitation Act requires a person filing for succession to operator status to submit the relevant operating permit, business report certificate, or registration certificate.
Where the succession results from a transfer, a copy of a document proving the transfer and acquisition is also required.
Depending on the business and circumstances, additional materials relating to hygiene education, authorization, or fire liability insurance may also be required.
This means that the private agreement between the parties and the administrative succession procedure should point to the same transaction.
What business did the parties agree to transfer?
And what regulatory status will the buyer claim to have succeeded to before the competent authority?
Those two answers should be consistent.
The contract therefore has four core functions.
First, Identify Exactly Which Permit, Registration, or Business Status Is Being Transferred
Business transfer agreements often contain broad language such as:
“The transferor transfers to the transferee all rights relating to the business.”
But from a regulatory perspective, that immediately raises another question.
What exactly does “the business” mean?
Suppose you are acquiring a restaurant.
You should confirm:
who is currently registered as the operator,
the trade name and business address,
the category of business,
the relevant permit, report, or registration number,
and whether the business described in the contract is the same business that actually exists in the administrative records.
This becomes even more important if one business holds multiple forms of administrative status.
The fact that the agreement states that the seller transfers “the entire business” does not automatically mean that every permit, registration, or statutory status under different laws will transfer as well.
The sequence should therefore be clear.
Identify the regulatory status that the buyer intends to acquire
↓
Confirm whether that status can legally be succeeded to
↓
Make sure the contractual subject matter matches the administrative status that will actually be transferred
Second, State the Regulatory Condition of the Business Being Acquired
Suppose regulatory due diligence has already been performed before the acquisition.
The operating report has been reviewed.
The building register has been checked.
The actual business premises have been inspected.
But the reported business area does not match the actual premises.
A separate storage area is being used.
It is unclear whether a required change filing was ever completed.
If all of these issues are discovered, but the agreement still states only:
“Goodwill: KRW 50 million. Final payment: ○○.”
then the due diligence process is only half complete.
The purpose of regulatory due diligence is not merely to identify problems.
The findings must be converted into transaction conditions.
When determining the acquisition price, the buyer usually has certain assumptions.
The existing business premises can continue to be used.
The current facilities can continue to be used.
The existing permit, registration, or operator status can be succeeded to and the same business can continue.
But if the buyer later discovers that a key part of the premises cannot legally be used,
additional facility work is required,
or another administrative procedure must be completed first,
then the business actually acquired may differ from the business the buyer believed they were purchasing.
Important due-diligence findings should therefore be reflected in the agreement.
What permits or registrations currently exist?
What changes have already been identified?
Are any corrective or supplementary procedures pending?
Who agreed to resolve the identified issues before closing?
In other words:
The agreement should record the assumptions on which the buyer agreed to pay the purchase price.
Third, Do Not Stop at “The Seller Will Cooperate” — Define the Action and the Deadline
If completion of regulatory succession requires cooperation from the seller, the contract should make that cooperation concrete.
However, many agreements simply state:
“The seller shall actively cooperate with the succession of operator status.”
That may seem sufficient when everything proceeds smoothly.
It becomes vague when the seller stops cooperating.
Which documents must be provided?
When must licensing or registration materials be delivered?
Must the seller provide additional signatures or seals if requested?
If the competent authority requests supplementary documents, must the seller provide them?
If an existing filing must first be corrected, who is responsible?
And most importantly:
By when must this cooperation be completed?
Regulatory clauses should therefore specify more than a general duty to “cooperate.”
They should identify:
who
must do what
and by when
The point is not to make the clause unnecessarily long.
It is to specify the actions and deadlines that matter.
Fourth, Connect the Seller’s Obligations to the Final Payment
This is the most important part of the transaction.
One of the highest-risk situations in the acquisition of a regulated business is:
the buyer has paid the full price, but important seller obligations required for the succession of the business remain outstanding.
The buyer’s practical position changes before and after the final payment.
Before paying the balance, the buyer may require the seller to provide regulatory documents first.
The parties can allocate responsibility for correcting identified problems.
The cost of required facility work may be reflected in the purchase price.
The seller can be required to complete specified obligations by a certain date.
The agreement can also determine what happens to the closing schedule if those issues are not resolved.
Now consider the opposite situation.
The buyer has paid the full purchase price and taken over the business.
Only afterward does the buyer discover that an additional signature from the seller is required.
More regulatory documents are needed.
An existing filing must first be corrected.
At that point, the buyer must obtain further cooperation after already paying the entire purchase price.
That is why the core purpose of regulatory review before closing is:
to complete the necessary conditions while the buyer has not yet paid the full amount.
This Does Not Mean Every Business Should Use the Same “Approval Before Final Payment” Clause
The legal point at which operator status is succeeded to, and the relevant filing or acceptance procedure, may differ depending on the applicable statute.
Therefore, using the same clause in every transaction—
“The buyer shall make the final payment only after the competent authority approves the succession.”
—is not necessarily correct.
But the underlying transaction principle remains the same.
Do not fully complete the buyer’s payment obligations while critical seller obligations required for regulatory succession remain outstanding.
The relevant administrative procedure should first be identified.
Then the transaction schedule should distinguish between:
what the seller must complete before the final payment
what should be completed simultaneously with closing
what the buyer must complete after succession
The administrative procedure may differ.
The sequencing principle does not.
A Good Agreement Prioritizes Performance Before Closing, Not Only Liability After a Dispute
When drafting a contract, parties often focus on what happens after something goes wrong.
What happens if the contract is breached?
How much is the penalty?
Who bears the loss?
These issues are important.
But in a regulated business transfer, something should come first.
The transaction should be structured so that the seller completes the necessary obligations before the problem arises.
The seller provides the necessary documents.
Identified regulatory problems are resolved.
Required signatures and seals are completed.
Contractually agreed pre-closing obligations are performed.
The parties then proceed with final payment and handover after checking performance.
A good business transfer agreement should therefore clearly answer:
“What must be completed before the buyer pays the final balance?”
The Agreement Should Also Explain What Happens If Regulatory Succession Does Not Proceed as Planned
Transactions do not always proceed exactly as expected.
The seller may fail to provide promised documents.
A previously undisclosed regulatory problem may be discovered.
A change filing may need to be completed first.
Additional facility work may be required.
The parties should therefore consider the following sequence at the contract stage.
Who will resolve the issue?
↓
By when must it be resolved?
↓
What happens to the final payment and handover date while the issue remains unresolved?
↓
How will additional costs be allocated between the parties?
↓
What happens if the fundamental purpose of the transaction can no longer be achieved?
The key is not to copy a generic “business transfer special clause” from the internet.
The regulatory risk identified in the actual transaction must be connected to the payment conditions.
If the matter has already developed into a dispute involving termination of the contract, repayment of money, or damages, the issue may no longer be limited to the administrative process and should be distinguished from matters requiring review by a Korean attorney.
Acceptance of the Regulatory Succession Does Not Automatically Cure Problems in the Underlying Contract
Consider the opposite problem.
The underlying business transfer agreement has a defect, but the competent authority has already accepted the succession filing.
Does that mean the contractual problem disappears?
In Supreme Court Decision 2005Du3554, December 23, 2005, the Court held that acceptance of a succession filing based on a transfer of business presupposes the existence of a valid and lawful business transfer.
Accordingly, if the underlying transfer does not exist or is invalid, acceptance of the succession filing may itself lack a valid legal basis.
The administrative succession of operator status therefore requires a properly established underlying transfer relationship.
Accordingly, neither of the following approaches is sufficient:
“The contract does not matter much as long as the authority accepts the succession.”
Nor:
“If the contract is well drafted, the regulatory succession can be dealt with later.”
The contract and the regulatory procedure should describe and implement the same transaction from the beginning.
Ultimately, the Agreement Must Perform Four Functions
You do not need to remember every detail above.
When reviewing a business transfer agreement, ask these four questions in order.
① What Is Being Transferred?
The relevant permit, registration, business report, or other regulatory status should be clearly identified.
② In What Condition Is It Being Transferred?
Important findings from regulatory due diligence, including issues that must be corrected, should be reflected as transaction assumptions or conditions.
③ What Must the Seller Do, and By When?
The documents to be provided, issues to be corrected, procedures requiring cooperation, and deadlines should be identifiable.
④ What Happens to Payment and the Transaction Schedule If Those Obligations Are Not Completed?
Critical seller obligations should be linked to the final payment, handover of the premises, and commencement of operations.
Whether the agreement contains five special clauses or twenty is not the important issue.
What matters is whether the agreement actually performs these four functions.
If Closing Is Approaching, Review These Four Warning Signs
1. You Were Simply Told, “The Succession Filing Can Be Done After Closing”
First determine what the seller must do before that filing can actually be completed.
2. The Contracting Party and the Name on the Permit or Registration Are Different
Identify who the actual registered operator is and who has the ability to transfer the relevant business status.
3. The Actual Business Premises Do Not Match the Regulatory Records
Do not finalize the payment schedule before the due-diligence findings have been reflected in the transaction conditions.
4. The Contract Has a Final Payment Date but No Deadline for the Seller’s Obligations
The deadline for payment matters.
But the deadline for the seller’s performance matters as well.
If the agreement has not yet been finalized or the final payment has not yet been made, this is an important stage at which regulatory issues can still be reflected in the contract and closing schedule.
Before Goodwill, the Agreement Should Secure Control Over the Transaction
The central principle of this article can be summarized in one sentence.
A problem that can be structured as a contractual condition before closing may become a cooperation problem or a dispute after the final payment.
Supreme Court Decision 2018Da259565 demonstrates that the cooperation of the existing operator may be necessary to complete the succession of operator status.
Before signing or completing a regulated business acquisition, the buyer should therefore be able to answer four questions.
What regulatory status am I acquiring?
What is its current condition?
What must the seller do, and by when?
What happens to the final payment and closing schedule if those obligations are not completed?
If those four questions remain unanswered, then even if the goodwill amount and purchase price are stated with absolute precision, an important part of the transaction remains unresolved from a regulatory perspective.
What You Can Review Yourself and When Professional Review May Be Necessary
If you already have a draft agreement, you can first check whether the relevant permit or registration is accurately identified, whether important findings from regulatory due diligence have been reflected in the contract, whether the seller’s cooperation obligations and deadlines are clear, and whether those obligations are connected to the final payment and handover.
However, if the contracting party is different from the registered operator, multiple permits or registrations are involved, the actual business operation does not match the administrative records, there are existing corrective or supplementary issues, or closing is approaching while necessary administrative procedures remain outstanding, the issue may not be resolved by adding a single generic clause.
In such cases, the transaction should be reviewed as one connected structure:
Current regulatory status → Actual business operation → Seller obligations → Succession procedure → Payment schedule
At ETHOS, we compare the current permit or registration, actual operating conditions, business transfer agreement, and proposed final-payment and handover schedule to identify the regulatory status that should be specified in the contract, the seller’s pre-closing obligations, issues that should be resolved before succession, and the appropriate sequence of payment.
Based on the current business transfer agreement, operating permit, business report or registration certificate, proposed final-payment date, and handover schedule, you can request a complimentary preliminary review to check what the seller should complete first and whether the regulatory succession procedure and payment sequence are properly aligned.